Most parents assume there is only one way to stop watching a college student's rent payments stack on top of tuition. They plan to buy an investment property, put 20% down, accept a higher interest rate, and hope the numbers work out. That assumption can cost families tens of thousands of dollars, and it is often avoidable.
The FHA non-occupant co-borrower strategy changes the math, and most Indiana families never hear about it until it is too late.
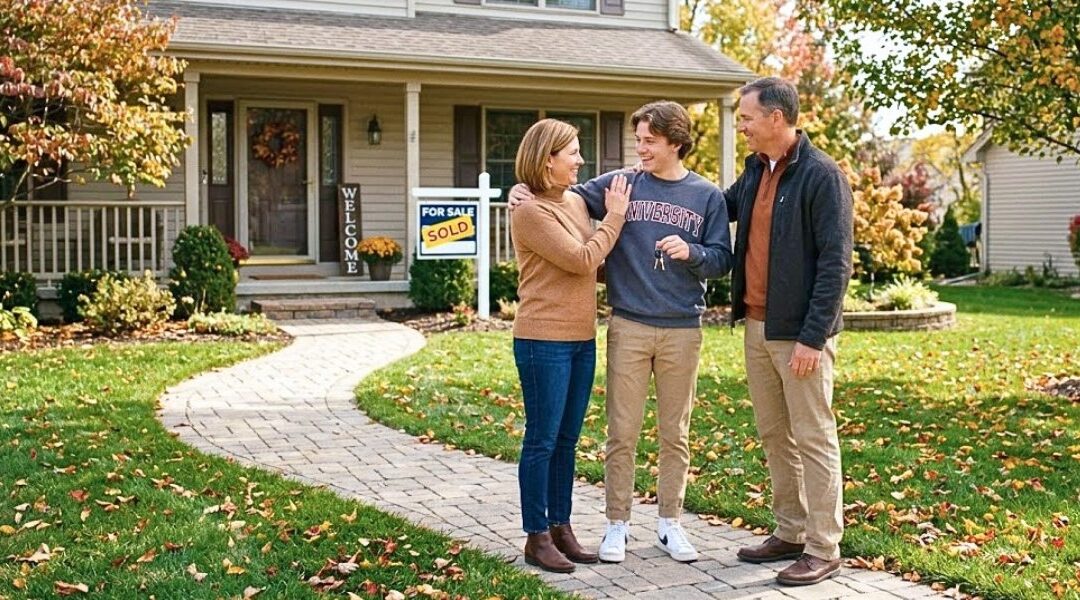
The FHA non-occupant co-borrower approach lets a student buy near-campus housing as a primary residence, with parents contributing income to qualify. It can require as little as 3.5% down instead of 20% and carries a primary residence rate instead of an investment rate. It also builds the student's credit history at the same time. Most families discover this option only after committing to a more expensive path.
Most Families Assume Buying Near Campus Means Becoming a Landlord
Parents who decide to stop watching rent disappear every month often default to one assumption: they need to become a landlord. That means an investment property loan, and investment property loans come with real costs.
Lenders often require 20% or more down on a non-primary residence, and rates run higher than primary residence rates. The parent carries all the financial risk, and the student builds nothing in the process.
Most families never consider that the student can be the borrower. A student with a qualifying credit score can purchase the property as a primary residence using an FHA loan. That structure can mean 3.5% down instead of 20% and a primary-residence rate instead of an investment-property rate.
FHA allows non-occupant co-borrowers, so the parents' income can drive the loan qualification even when the student has little or no income of their own. The student builds credit, the parents keep more cash, and the family pays a lower rate than on an investment loan. The main catch is that the student must live in the home as a primary residence.
FHA also carries mortgage insurance on every loan, so families should compare the full monthly cost of both paths. Running both scenarios side by side shows which path fits your family's numbers.
The FHA Non-Occupant Co-Borrower Strategy Works Through Combined Income
The mechanics are straightforward once you understand how the pieces fit together. FHA guidelines allow a co-borrower who does not live in the property to contribute income to the loan qualification. That co-borrower, typically a parent, provides enough income to qualify for a home the student could not purchase alone.
One detail matters more than any other, because a non-occupant co-borrower provides income support but cannot fix a credit problem. FHA uses the lowest minimum decision credit score among all borrowers, so a parent cannot raise a student's score by joining the loan. Every borrower on the loan must meet FHA's credit standards, so the student's score and the parents' scores both matter.
For families where the student has established credit and the parents carry solid income, this structure works cleanly. The student is the primary borrower, and the property finances as a primary residence. The parents' income fills the qualification gap.
Parents on the loan are fully liable for it and share ownership of the property. Under HUD Handbook 4000.1, the 96.5% loan-to-value limit applies to non-occupant co-borrowers only when the borrowers are family members, and not for two-to-four-unit properties.
The debt-to-income ratio (DTI) calculation under FHA uses combined income from both the occupying borrower and the non-occupant co-borrower. That combined picture is often what makes a purchase price work that would otherwise fall outside the student's reach. The Loan Estimate required under the TILA-RESPA Integrated Disclosure rule also helps families see total loan costs early, before they commit to either path.
Tevis Durbin has guided Indiana families through this approach from both the Fishers and Elkhart offices. He has worked through the numbers with dozens of families who expected to hear that an investment property was their only option. The contrast between the two paths becomes clear once the numbers sit side by side.
"If one of your kids has a high enough credit score, you could have them buy the house FHA. They're a first-time homebuyer, they put three and a half percent down, not 20. It's a primary residence for them, not investment, so they get a better rate. And even though they don't have a job, we're using the income for mom and dad as a non-occupant co-borrower. It's a win-win." – Tevis Durbin, Producing Branch Manager (NMLS #424899)
FHA Works Better Than Conventional for This Strategy
Families occasionally ask whether a conventional loan could accomplish the same thing. The answer depends on the program, and the details can get complicated.
Conventional programs set their own rules for non-occupant co-borrowers, and those rules shift by loan product and property type. Running into a restriction mid-transaction creates real delays that can be difficult to resolve.
FHA rules for non-occupant co-borrowers are well defined, including the family-member requirement for 96.5% financing. The loan-to-value ratio (LTV) picture also looks different. A 3.5% down payment on an FHA loan means a 96.5% LTV. A conventional investment property with 20% down starts at 80% LTV, but it requires a much larger cash outlay. For many families, the difference in upfront cash is the deciding factor.
Four Variables Determine Whether This Works for Your Family
The strategy isn't universal, and a few key inputs determine whether the numbers work. You can evaluate all of these variables before anyone starts shopping. The four inputs that matter most appear in the list below.
- Credit Scores: FHA requires a minimum decision credit score of 580 for the 3.5% down payment tier, and the lowest score among all borrowers sets that number. Under FHA rules, scores between 500 and 579 require at least 10% down. A soft credit pull shows where things stand without affecting your score.
- Parents' Qualifying Income: The student likely has little or no employment income, so the parents' income carries the loan. Debt-to-income ratios, existing obligations, and the target purchase price all factor into whether the qualification math works.
- FHA Loan Limits: FHA loan limits vary by county across Indiana, so a property near a campus in a higher-cost area may need a closer look. The 2026 one-unit limit starts at $541,287 in lower-cost counties. HUD's FHA loan limit lookup lets families check county-specific limits before they start shopping.
- Property Type: Single-family homes and FHA-approved condos are typically the cleanest fit. A two-to-four-unit property with a non-occupant co-borrower is limited to 75% loan-to-value, which means a much larger down payment.
FAQs About the FHA Non-Occupant Co-Borrower Strategy
Does the student need a job to qualify as the primary borrower?
No, the student does not need employment income when the parents serve as non-occupant co-borrowers, because their income qualifies the loan. The student does need credit that meets FHA standards, and the lowest score among all borrowers sets the requirement. Income and credit serve different functions, and a parent's income can support the loan while a parent's score cannot lift the student's.
What credit score does the student need for an FHA loan with a non-occupant co-borrower?
FHA requires a minimum decision credit score of 580 for the 3.5% down payment tier, and the lowest score among all borrowers counts. Scores between 500 and 579 require at least 10% down, which changes the math on the entire strategy. A soft credit pull gives a clear picture without affecting anyone's score.
Can both parents be on the loan as non-occupant co-borrowers?
Yes, both parents can be included as non-occupant co-borrowers, which means both incomes contribute to the qualification calculation. Combining both incomes can increase the purchase price the student qualifies for. Each added parent's credit score also becomes part of the lowest-score calculation. Both parents also become liable for the full loan.
What happens to the property when the student graduates?
The options are flexible, because the student can sell the property, continue living in it, rent it to future students, or refinance if circumstances change. FHA expects the student to occupy the home as a principal residence for at least one year before renting it out. The student exits college with a mortgage history, equity that builds as the loan pays down, and a real asset instead of an apartment lease. Our look at two financing paths for first-time buyers shows how that equity picture can develop over time.
What if the student's credit score is not high enough yet?
In many cases, this is solvable. A review of the student's credit file identifies what is pulling the score down and which steps could move it in the right direction. A few months of targeted effort can close the gap in many situations. Starting early creates more options and removes the pressure of a tight timeline.
How does this strategy affect the parents' ability to qualify for their own mortgage later?
Adding a loan as a non-occupant co-borrower does affect the parents' debt-to-income ratio. It shows up on their credit report as a mortgage obligation. Parents who plan to refinance or purchase another property in the next few years need to factor that added obligation into the planning.
Is this FHA strategy available near any Indiana university?
FHA is available statewide, so the approach works near Purdue, IU, Ball State, Notre Dame, and other Indiana campuses. Prices and loan limits vary by county, which is why the planning conversation starts with the specific market. That early review minimizes surprises once you find a property.
Run the Numbers Before You Commit to the Investment Property Path
The families who wish they had known sooner are the ones who signed an investment property purchase agreement first. The window on the FHA option closes once a parent signs a purchase agreement at 20% down. The comparison is worth running before any contract exists, because the family may save cash and give the student a credit history.
If a student is heading to campus within the next year, or already paying rent, now is the ideal time to review your options. Our team runs through these scenarios with Indiana families every week, and the answer is often better than the family expected. Contact Supreme Indiana to review your credit picture, income qualification, and county loan limits together.