Your tax returns may show much less taxable income than the deposits flowing through your business account. Traditional mortgage underwriting can make qualifying difficult when business deductions significantly reduce taxable income.
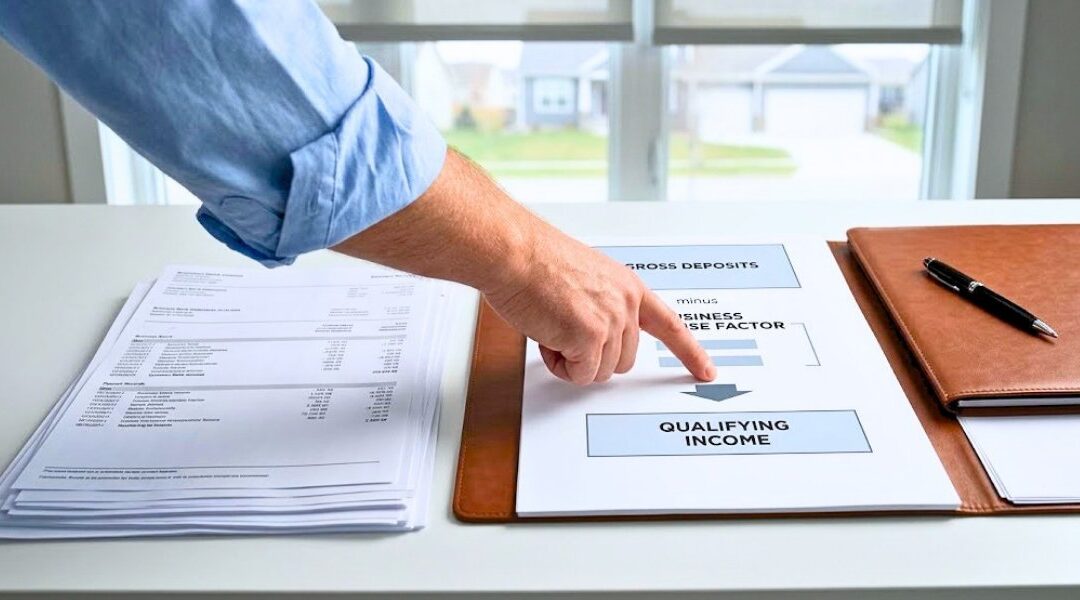
Calculating income for a bank statement loan is more structured than many self-employed borrowers realize. A lender moves from raw deposits to a qualifying income figure through a defined underwriting process.
Bank statement loans can qualify self-employed borrowers using bank deposit history instead of traditional tax-return income calculations. Lenders apply program-specific expense assumptions to deposits to determine qualifying income. The process involves documentation and underwriting requirements that borrowers should understand before choosing this financing option.
What Non-QM Means for Self-Employed Borrowers
The term Non-QM carries a lot of baggage, much of it undeserved. After the 2008 financial crisis, the Dodd-Frank Act established ability-to-repay requirements and directed regulators to establish Qualified Mortgage standards. A Non-QM loan is a mortgage that does not meet the applicable Qualified Mortgage requirements.
That does not automatically mean a borrower has poor credit or that the loan is inherently risky. It means the income documentation may look different. Bank statement loans, 1099 programs, profit-and-loss loans, and asset depletion loans can fall under the Non-QM umbrella, depending on the specific program.
Tevis explains the distinction directly:
“NonQM doesn’t necessarily mean high credit, low credit scores. It doesn’t mean bad loans. It typically means there’s going to be alternative income documentation. In our nonQM products, that’s what we’re trying to do: give people an option to still buy a house and use some non-traditional products.”
— Tevis Durbin, Producing Branch Manager (NMLS #424899)
How Lenders Turn Bank Deposits Into Qualifying Income
Most borrowers get lost here because they assume the lender simply averages deposits and calls the result qualifying income. The calculation involves additional underwriting steps.
The process starts with deposit history, typically covering 12 or 24 months, depending on the loan program. The lender reviews the deposits to determine which amounts can be used to calculate qualifying income. In programs that use an expense factor, the lender considers the business profile and applies the applicable percentage to gross deposits.
A solo real estate professional with no employees might receive a 30% expense factor. That means $10,000 in monthly deposits produces $7,000 in qualifying income, or $84,000 per year. Tevis illustrates the calculation using an engineering business with substantial overhead:
“They were doing about $500,000 a month in deposits, but he had 10 employees, overhead, warehouses, licensing, a pretty legit operation. We took an 80% expense factor, so of that $500,000, we ended up counting about $15,000 a month for income, which was $180,000 a year. That was enough for him to qualify. He was buying a lake home.”
— Tevis Durbin, Producing Branch Manager (NMLS #424899)
The final qualifying income can also depend on other program-specific adjustments and underwriting requirements. In programs that use an expense factor, gross deposits are adjusted based on estimated business expenses to determine qualifying income.
What Goes Into a Bank Statement Loan File
A strong bank statement file includes several documentation and qualification factors that can affect approval and pricing.
- 12 or 24 months of bank statements. Some programs allow 12 months, while 24 months provides more deposit history for the income calculation.
- A completed business narrative. This document describes the business type, number of employees, and general overhead structure. It helps the lender determine the appropriate expense factor, so accuracy matters. Some programs allow a CPA letter to document lower-than-average expenses, which can result in a more favorable income calculation.
- At least 25% ownership in the business. Borrowers with minority ownership stakes do not qualify under this program regardless of deposit volume.
- Credit and down payment requirements. A score above 680 may provide access to more favorable terms within some bank statement programs. Many programs require 20% down, although some options may allow 10%.
Before assuming conventional financing is your only option, review your options with Tevis Durbin. He can review your financial profile and discuss which programs may fit your situation.
Comparing the Cost of Buying Now or Waiting
Bank statement loans often carry higher interest rates than conventional financing, although the difference varies by borrower and loan program. That sounds like a significant premium until you run the comparison.
The more relevant comparison may be the cost of buying now versus changing your tax returns and qualifying later. For some borrowers, that alternative may involve amending prior returns, paying additional taxes and potentially related interest or penalties, then qualifying later.
Tevis walks borrowers through that comparison, including factors that can affect the calculation. Mortgage interest may also be deductible for eligible homeowners, depending on how the property is used and current IRS rules. A CPA can help determine whether that deduction applies to your situation.
A related example shows how a profit and loss loan helped a self-employed borrower close in 30 days.
Bank Statement Loan Questions Worth Asking
Do I need to refile my taxes to qualify for a bank statement loan?
Bank statement loans can provide an alternative for self-employed borrowers whose taxable income does not support the mortgage amount they need. Qualification can be based on eligible bank deposits and other program requirements rather than the adjusted gross income shown on a tax return. You generally do not need to amend your tax returns simply to use a bank statement loan program.
What is an expense ratio, and who decides what mine is?
In programs that use an expense factor, the lender determines the applicable percentage based on the program and business profile. Factors can include the business type, number of employees, and overhead structure. Some programs allow a CPA letter to document lower expenses, which may result in a more favorable qualifying income calculation.
How many months of bank statements do lenders typically require?
Bank statement programs commonly use 12 or 24 months of statements, depending on the program. Some 24-month programs may offer lower rates than comparable 12-month options. More history also gives the lender more deposit information to evaluate.
Can I use business bank statements if my company is structured as an S-Corp?
Yes, depending on the bank statement program. Business statements may be used when the borrower meets the program's ownership and documentation requirements. For this program, at least 25% ownership is required. Personal or business statements may be acceptable depending on where the business income is deposited.
Can I use a bank statement loan on an investment property?
Some lenders offer bank statement programs for investment properties, although terms vary. Down payment and reserve requirements may be higher. Investors may also compare a DSCR loan, which generally qualifies based on rental income rather than personal or business income. Indiana investors can see what most get wrong about LLC and DSCR financing before choosing a program.
Is a bank statement loan a good bridge if I plan to refinance in two years?
It can be, if the borrower expects to qualify for conventional financing after improving the income profile shown on tax returns. The refinance plan should be evaluated before closing, including income requirements, credit profile, equity position, and other factors that could affect future eligibility. A future refinance should be treated as a goal rather than a guarantee.
Your Income Built a Business. Now Let It Buy a House.
If your taxable income does not support the mortgage amount you need, a bank statement loan may offer another option. The income calculation is structured and specific, with program requirements that determine how deposits are evaluated.
Review your deposit history and find a financing strategy that fits your business. Connect with Supreme Indiana to get started.