If your earnings include overtime, bonuses, commissions, or second-job income, mortgage qualification works differently than it does for straight salary. Lenders must document that the income is stable, has an established history, and is reasonably expected to continue.
That review can create a gap between the income you earn and the amount lenders may use for qualification. Variable income mortgage qualifying in Indiana follows federal ability-to-repay standards and the requirements of the selected loan program. Understanding the documentation before applying can place you in a stronger position from the beginning.
Qualifying for a mortgage with variable income works differently than standard fixed-salary rules. Most loan programs require a two-year history, but shorter options may exist. Lenders evaluate your overall income trend rather than defaulting to the lowest number. Gathering your records early helps your lender calculate true buying power before you make an offer.
Income History Rules for Variable Pay
The standard guideline for variable income is a two-year history, although the exact requirement depends on the income type. If you just started getting overtime or received your first bonus on the job, those income sources may not immediately count toward mortgage qualification.
The lender must confirm a reliable history and determine whether the income pattern appears stable enough for qualification. The Consumer Financial Protection Bureau's ability-to-repay guidance explains that lenders generally verify income, assets, employment, debts, and monthly expenses.
Fannie Mae recommends a two-year history for bonus, commission, overtime, and tip income. However, Fannie Mae's variable income guidelines may allow income received for at least 12 months when positive factors support the shorter period. Income received for less than 12 months generally presents fewer conventional options under these guidelines.
The lender then compares year-to-date earnings with prior earnings to identify a stable, increasing, or decreasing trend. Stable or increasing income may be averaged using the applicable documented period, which must include at least 12 months.
When income decreases, the lender must confirm that the current amount has stabilized before using it for qualification. This approach helps align the approved payment with income that the documentation reasonably supports.
Variable Income Sources Lenders May Consider
The list is broader than many buyers expect and can include several forms of additional employment earnings. Overtime, shift differentials, bonuses, commissions, restricted stock units, stock compensation, and income from additional jobs may require separate reviews.
A written compensation agreement can help establish whether certain earnings are fixed, guaranteed, or variable. Nurses and healthcare professionals across Hamilton County may receive shift differentials and overtime as meaningful parts of their total earnings.
That income may support qualification when the history, trend, and documentation meet the selected program's requirements. The same principle applies to corporate employees receiving annual bonuses or equity compensation tied to time or performance.
Required and discretionary overtime still need appropriate documentation, but written employer details can help clarify the income pattern. Restricted stock units add another documentation layer because award type, vesting history, distribution, and future vesting can affect qualification.
Under Fannie Mae's restricted stock guidelines, time-based awards generally require a 12-month history from the current employer. Performance-based awards usually have a recommended two-year history, although at least 12 months may work with supporting positive factors.
If equity compensation represents a meaningful portion of your earnings, bring grant agreements, vesting schedules, and distribution records to your lender.
Multiple Jobs Add More Documentation
Borrowers using income from multiple jobs often need a closer review of each income source. Each job must meet the requirements for its specific income type, including the applicable history and stability standards.
Fannie Mae recommends a two-year history for each job, but at least 12 months may qualify with positive factors. When the employment history includes different employers, a gap exceeding one month during the latest 12 months may require additional review. Frequent job changes do not automatically prevent qualification when the borrower continues earning consistent and predictable income.
Tevis Durbin has worked through many income structures during more than 26 years in mortgage lending. A recent case involving a borrower with three jobs shows why early review matters.
"A deal was blowing up and they wanted us to figure out, could we save it? It was a lady that works three jobs. You have to work all three jobs for 24 months in a row, no gaps. We dug into it, and she had 15 different payroll providers in the last two years. When we went through that whole research, because she had some gaps, you couldn't count that third job until October. They should have known that two or three weeks ago."
— Tevis Durbin, Producing Branch Manager (NMLS #424899)
Not sure how several income sources may be treated during qualification? Review them with The Durbin Team before writing an offer, so your home search begins with clearer numbers.
Variable Income Documentation to Gather Early
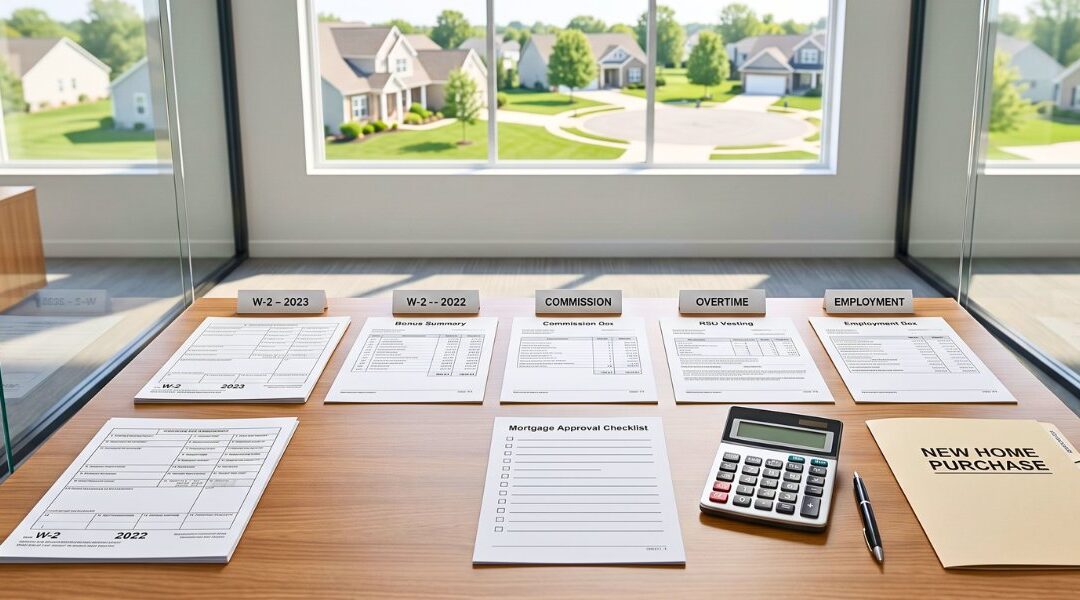
The practical steps become easier once you understand which details lenders evaluate for each income source. Before your first lender conversation, gather the following documents for a complete income review:
- Employment Income: Bring your 2 most recent years of W-2s and recent pay stubs from every employer.
- Tax Records: Provide tax returns when required for your income type, business interests, or selected loan program.
- Bonus and Overtime Income: Gather compensation agreements and employer records confirming your income history and current pay structure.
- Multiple-job Income: Create an employment timeline showing each employer, position, start date, and any gaps between jobs.
- Restricted Stock Income: Bring grant agreements, vesting schedules, and records showing previous stock distributions.
- Additional Income Records: Include documents supporting commissions, shift differentials, seasonal earnings, or other variable compensation.
A short employment gap does not always remove an income source, but the lender must review it under the applicable guidelines. Most importantly, begin the conversation early enough for the lender to review every income source carefully.
"The typical rule of thumb is: first of all, is it mandatory? Is it part of their compensation package? If I get a minimum $10,000 bonus every quarter, that's in writing, that's a minimum, it's part of my pay, we can count that. But when it's truly variable in nature, you just have to have a history of it. It's typically a two-year average, and we're going to take the lesser of that. It's a conservative approach because we want to make sure you can handle it."
— Tevis Durbin, Producing Branch Manager (NMLS #424899)
Variable Income Mortgage Questions from Indiana Buyers
How long does variable income need to be documented for Indiana mortgage qualifying?
A two-year history is commonly recommended for overtime, bonuses, commissions, tips, and income from multiple jobs. Fannie Mae may consider histories between 12 and 24 months when positive factors support the shorter period. Seasonal earnings, restricted stock, variable hourly pay, and other compensation may support qualification with the appropriate documentation. For a broader overview of qualification, read our post about the two financing paths first-time buyers should know about.
What is the averaging rule for variable income?
The lender compares current year-to-date earnings with prior earnings and reviews whether the trend is stable, increasing, or decreasing. Stable or increasing income may be averaged across the applicable documented period, including at least 12 months. For declining income, the lender must confirm stabilization and may use the current stabilized amount instead.
Does switching jobs reset the clock on bonus or overtime income?
A job change does not automatically erase every part of your prior employment or income history. The lender reviews whether the new position, pay structure, and variable earnings support consistent and predictable income. Additional time at the new employer may be needed when the earnings type or compensation structure changes significantly.
Can I qualify for a mortgage using income from two or three jobs?
Income from several jobs may support qualification when each source meets the applicable history, stability, and documentation rules. Fannie Mae recommends a two-year history for each source but may consider a minimum of 12 months with positive factors. Employment gaps and job changes require review, but a brief gap does not automatically disqualify an income source.
How can RSUs and restricted stock support mortgage qualification?
Restricted stock income may support qualification after the shares vest and become available without restrictions. Time-based awards generally require at least 12 months from the current employer under current Fannie Mae guidelines. Performance-based awards usually carry a recommended two-year history, with shorter periods possible when positive factors support them. The lender also reviews vesting schedules, distribution history, award type, and future continuation requirements.
What documentation do I need when my income includes bonuses?
Gather recent pay stubs, your 2 most recent years of W-2s, and any written compensation agreement from your employer. The lender may also obtain a verification of employment to confirm the bonus history or clarify the current pattern. A guaranteed amount may receive different treatment than a discretionary bonus, depending on the compensation agreement and selected program.
Does required overtime qualify differently from discretionary overtime?
Written confirmation that overtime is required and ongoing may make its pattern easier for the lender to document. However, the lender still reviews the applicable history, current trend, and likelihood that the income will continue. Discretionary overtime may also qualify when the documentation supports a stable and acceptable pattern.
When should I discuss variable income with a lender?
Begin before making an offer, especially when variable earnings are needed to reach your intended price range. An early review can identify the documented amount, missing records, and any additional history your chosen program may require. Borrowers approaching a 12-month or 24-month milestone may also benefit from reviewing their timing before shopping.
Variable Income Can Support a Strong Mortgage File
Variable income mortgage qualifying is an area where careful documentation and lender experience can make the process easier. The published guidelines provide a framework, but every borrower brings a different mix of earnings, employers, and employment history.
If variable income supports your buying power, understand the qualifying amount before making an offer on an Indiana home. A clear review of your earnings, records, and timeline can help you shop within a more reliable price range.
Reach out to The Durbin Team for a practical review before your home search moves forward. The earlier your income is reviewed, the more time you have to prepare a mortgage plan around your actual numbers.
Tevis Durbin is the producing branch manager of Supreme Lending at Supreme Lending. He holds a Certified Mortgage Advisor (CMA) designation and an MBA in Finance, and serves on the State Board for the Mortgage Bankers of Indiana with a 97.75% five-star client rating built across more than two decades of mortgage practice.
ABOUT THE AUTHOR
Tevis Durbin (NMLS #424899) is a Producing Branch Manager at Supreme Lending with over 26 years of experience in the mortgage industry. Leading "The Durbin Team," Tevis combines his deep financial background — holding an MBA in Finance and a degree in Economics — with specialized loan programs to help Midwest homebuyers navigate complex markets. He is a Certified Mortgage Advisor, serves on the State Board for the Mortgage Bankers of Indiana, and acts as the Communication Chair for the Hamilton County division of MIBOR.