Mortgage recasting is one of the most effective tools available to Hamilton County homeowners who locked in low rates between 2020 and 2022. Most have never heard of it, but it can be one of the smartest financial moves if you have the money.
Maybe you recently received a bonus at work or an inheritance. You are likely considering the best way to use it. People often think about spending or investing first. Applying it to your mortgage also has real value. Most make that decision without knowing this option exists.
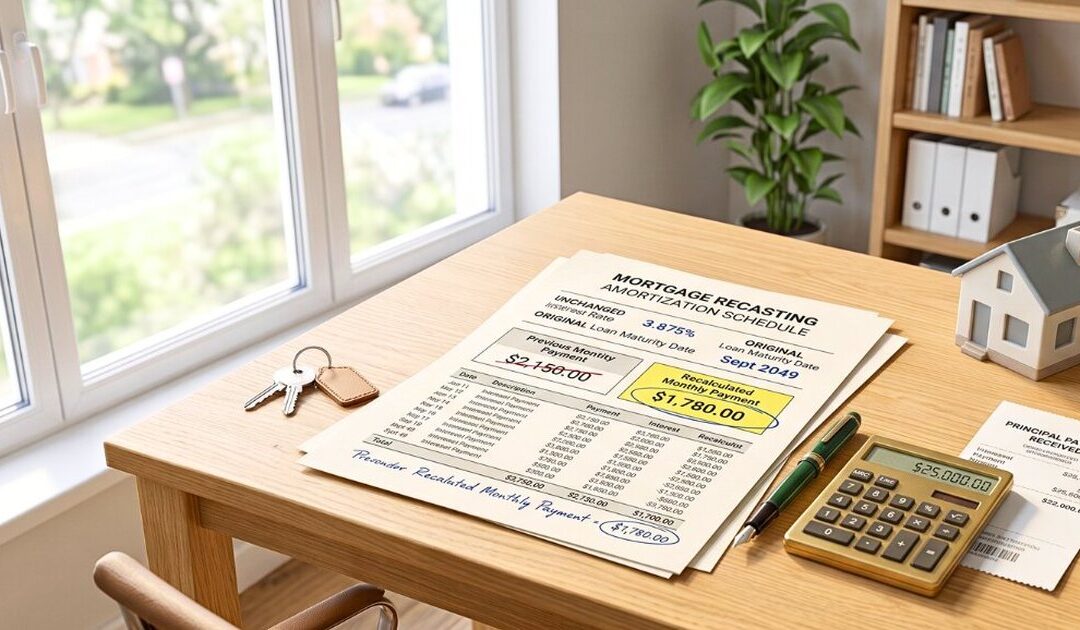
Mortgage recasting reduces your required monthly payment by applying a lump sum to your principal and recalculating what you owe. It does not change your interest rate or restart your loan term. Homeowners who locked in sub-4% rates are ideal candidates, especially those who recently received a bonus, inheritance, or home sale proceeds. Recasting typically costs less than $500 and preserves the low rate that refinancing would eliminate.
Recasting Lowers Your Payment Without Refinancing
A mortgage recast takes a lump sum applied to your principal and reamortizes the remaining balance over the rest of your existing loan term. You are not resetting the clock to a new 30 years. You are not refinancing. Your interest rate stays the same, and your loan end date does not change. What changes is the required monthly payment, recalculated on the lower balance across the remaining years.
That lower payment kicks in immediately and stays lower for the life of the loan. That is the piece most homeowners miss when they first hear about recasting. Making extra principal payments without a recast builds equity, which matters, but your required monthly payment never changes. You are paying ahead with no reduction in your monthly obligation.
A recast delivers both a lower balance and a lower minimum payment, starting the following month. The process involves your loan servicer recalculating your amortization schedule based on the new, reduced principal.
What the Numbers Look Like for Hamilton County Homeowners
The math changes significantly based on your loan balance and the size of the lump sum. Most Hamilton County buyers who purchased between 2020 and 2022 are working with balances in the $300,000 to $600,000 range. The payment reductions at those levels are meaningful.
Tevis Durbin has worked these numbers across hundreds of local loan structures. He draws on real transactions to explain what recasting actually produces:
“A person bought a $2 million house and sold their other house, then put a million dollars toward the recast. That dropped their payment by about $2,000 a month. But most of the time, people put in $20,000, $50,000, $70,000, and depending on how big the loan is, it’s saving them $500 a month.” – Tevis Durbin, Producing Branch Manager (NMLS #424899)
A $500-a-month reduction on a standard Hamilton County loan balance is meaningful. Over five years, that is $30,000 in payment flexibility returned to the homeowner, while the low interest rate remains intact.
The lump sum doesn’t disappear into the loan. It restructures the monthly obligation so that it compounds over the loan’s remaining term.
Buyers in Fishers, Carmel, Westfield, and Noblesville who purchased at the low end of the rate cycle can reach these numbers with a single transaction.
When Mortgage Recasting Beats Making Extra Payments
This is the comparison most people skip, and that’s where the opportunity cost lies. A recast that reduces your required payment by $500 per month rewards you even more if you keep paying the original higher amount. That extra $500 then goes entirely to principal every month going forward. You get the compounding effect on top of the already lower balance.
That is a different trajectory than just making extra payments without the recast. Extra principal payments without recasting eventually get you to the same equity destination. The difference is that you never receive the monthly cash-flow relief, and you lose the flexibility to reduce your obligation if circumstances change.
One scenario favors skipping the recast. A lump sum that can earn a stronger market return than the rate you would eliminate makes that a legitimate calculation worth running. For homeowners whose primary goal is reducing monthly obligations while protecting a locked-in low rate, recasting is almost always the cleaner path.
A recast lowers your payment, but equity still builds through appreciation and principal paydown over the years you hold the home. A realistic 2.8% appreciation forecast, rather than the rosier historical average, is the honest way to project that growth.
Not sure whether recasting makes sense for your specific balance and goals? You can talk to The Durbin Team before you decide how to deploy that lump sum.
Common Mistakes Homeowners Make With a Low Rate and a Lump Sum
Two mistakes come up consistently, and both are preventable. The first is refinancing. Refinancing a 2% or 3% rate to lower your payment means trading that rate for today’s market rate. You eliminate the core advantage you are trying to protect.
Most homeowners recognize this instinctively when it is explained directly. What they do not always recognize is that the alternative they default to, leaving the money in savings, is often not better either. That leads to the second mistake: inaction.
The lump sum sits in a high-yield savings account earning 4%. Meanwhile, the homeowner continues to carry mortgage debt at a rate they locked in during a different era. Sometimes the math favors the savings account. Often it does not. Very few homeowners actually run the comparison before deciding.
“Most people don’t know about recasting. The biggest mistake they make is just not knowing what their options are. They’re truly lowering their payment; there’s really no downside to that.” – Tevis Durbin, Producing Branch Manager (NMLS #424899)
That is the kind of gap that costs homeowners real money over time, not because of bad decisions, but because the option never surfaced. Recasting costs far less than a refinance, preserves your existing rate, and lowers your monthly payment going forward.
Who Qualifies for a Mortgage Recast in Indiana
Not every loan type is eligible. Conventional loans serviced by Fannie Mae and Freddie Mac are the most commonly eligible. Those servicers are generally equipped to process a recast with minimal friction. FHA loans and VA loans do not allow recasting under standard program guidelines. Jumbo loans vary by lender and servicer.
The minimum lump sum required to trigger a recast depends on your servicer’s policies. The range most commonly seen is $5,000 to $10,000. Administrative fees typically range from $150 to $500, a fraction of the closing costs associated with a refinance.
A quick conversation with your servicer or a mortgage advisor can confirm your eligibility in minutes.
Common Questions About Mortgage Recasting
Does a recast extend my loan term back to 30 years?
No. A recast reamortizes your remaining balance over the remaining term of your existing loan. With 22 years remaining on your original 30-year mortgage, the loan stays at 22 years after the recast. You are not adding time or restarting the clock. The payment calculation reflects the lower principal balance across your remaining schedule.
Will recasting affect my interest rate?
Your rate stays exactly where it is. That is the primary reason homeowners with low locked rates consider recasting rather than refinancing. A refinance replaces your existing loan with a new one at current market rates, giving up the rate you already hold. A recast leaves that rate untouched.
Is there a minimum lump sum required to trigger a recast?
Yes, and it varies by servicer. Most conventional loan servicers require a minimum of $5,000 to $10,000, and some require more. Your loan servicer can confirm the exact threshold for your account.
What does it cost to recast a mortgage?
Most servicers charge an administrative fee between $150 and $500, which is the typical total cost. There is no appraisal, no credit check, no title work, and no closing disclosure required. That administrative simplicity is one reason recasting is faster and cheaper than a refinance. A refinance can carry $3,000 to $7,000 in closing costs.
Can I recast if my loan type is FHA or VA?
Not all loan programs are eligible for recasting. FHA and VA cannot be recast under standard program guidelines. Conventional loans are the most commonly eligible loan type, and jumbo loan eligibility depends on the specific servicer. An FHA or VA loan with a lump sum to deploy shifts the conversation toward extra principal payments or other strategies.
What is the difference between a mortgage recast and a refinance?
A refinance replaces your existing loan with a new one, establishing a new rate, term, and closing costs. A recast keeps your existing loan unchanged and recalculates the monthly payment based on a reduced principal balance. For anyone holding a sub-4% rate, a refinance eliminates the rate advantage you have. A recast protects it while still lowering what you owe each month.
How long does a mortgage recast take to process?
Most servicers complete a recast within 30 to 60 days of receiving the lump sum and the required documentation, and some process it faster. The new payment amount typically takes effect in the billing cycle following the recast’s finalization. This is considerably faster than a refinance, which typically requires 30 to 60 days for underwriting alone.
Run the Numbers on Your Hamilton County Mortgage
When you find yourself with a large amount of cash, the right choice comes down to several variables. If you have a low rate, mortgage recasting deserves a place in that conversation. It offers a way to improve the loan without sacrificing the rate or having to start over.
Supreme Lending works with homeowners across Hamilton County to model these decisions. We can help you break down how recasting compares to other options using your actual numbers. Connect with our team to review your situation before making a decision.
ABOUT THE AUTHOR
Tevis Durbin (NMLS #424899) is a Producing Branch Manager at Supreme Lending with over 26 years of experience in the mortgage industry. Leading “The Durbin Team,” Tevis combines his deep financial background – holding an MBA in Finance and a degree in Economics – with specialized loan programs to help Midwest homebuyers navigate complex markets. He is a Certified Mortgage Advisor, serves on the State Board for the Mortgage Bankers of Indiana, and acts as the Communication Chair for the Hamilton County division of MIBOR.