Blog Articles
What Indiana Real Estate Investors Get Wrong About LLC and DSCR Financing
Most Indiana investors assume an LLC removes the mortgage from their personal credit. It does not. Learn how LLC vesting and DSCR loans work together, what underwriting actually reviews, and how to structure your next investment deal correctly.
Zero Down in Indiana When IHCDA Is Not an Option
Not every Indiana buyer qualifies for IHCDA’s zero-down program. The Supreme 100 loan offers a second path with different credit, income, and first-time buyer requirements. Here’s how a mortgage advisor decides which option fits your situation.
Indiana Veterans Can Use Their VA Loan Benefit Again
Indiana veterans with an active VA loan may still be able to purchase another property using remaining entitlement – sometimes with no money down. Here is how the VA loan partial entitlement calculation works in 2026 and why getting it in writing matters.
Fishers Home Buyers Have Real Leverage in 2026
Fishers home buyers have more negotiating power right now than they have seen in years. Here is how to choose between a price reduction, seller-paid closing costs, a rate buydown, or repair credits – based on math, not instinct.
Zero Down in Indiana Doesn’t Have to Mean FHA
Most Indiana buyers assume zero down means FHA. It doesn’t. Conventional no-down-payment programs exist right now – including Indiana Housing’s conventional option and the Supreme 100 – and they open up more homes, better terms, and a cleaner path to closing.
Indiana Buyers Are Getting Lower Payments With Money Still in the Bank
Indiana buyers with money saved are using a counterintuitive strategy to lower monthly payments: combining IHCDA down payment assistance, seller concessions, and personal savings at the same time. Here’s how the stacking approach works and why the window is open right now.
When a VA Deal Nearly Collapsed and Experience Closed It
A VA loan deal was hours from dying. A seller was relisting, a family was in a hotel, and the Florida closing hadn’t happened yet. Here’s what 26 years of mortgage experience looks like when a transaction is truly on the edge.
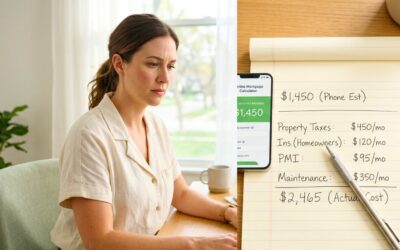
What Mortgage Calculators Get Wrong and What It Costs You
Online mortgage calculators often miss property taxes, insurance, and credit score pricing tiers by hundreds of dollars a month. Here’s what a real payment estimate actually requires, and how to protect yourself before the gap costs you.
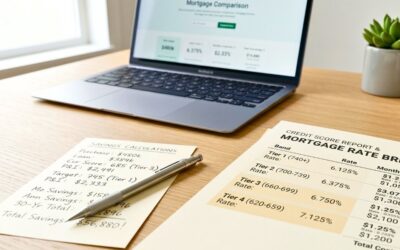
Your Credit Score Drives Your Rate Long Before You Apply
Your credit score doesn’t just determine approval – it drives your rate and closing costs through a pricing tier system most lenders never explain. For Indiana buyers, understanding this before you apply can save thousands.
Contact us to explore all your loan and down payment assistance options
and start your path to homeownership today.